BLOCK 042024· Participant

Mathematical Finance Programme, Oxford

A month at the Mathematical Institute: mathematical statistics, machine learning, and quantitative finance.

Year
2024
Role
Participant
Status
Archived

Fig. 01 · 2024

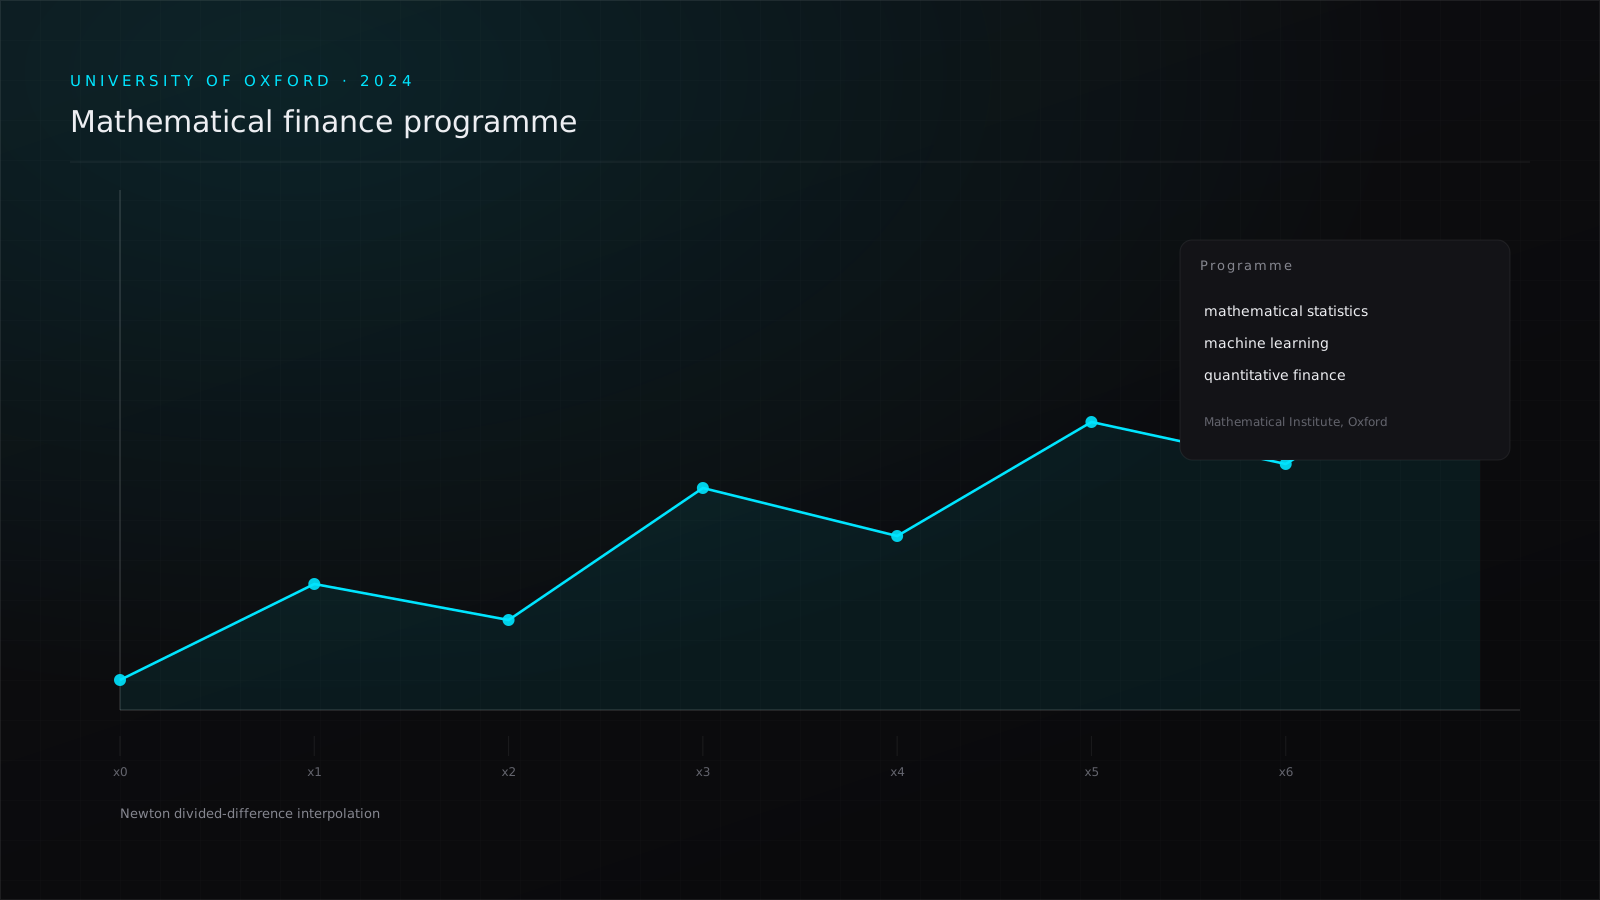
A polynomial curve fitted through sampled points by Newton divided-difference interpolation, with the interpolation intervals marked along the horizontal axis.
Newton divided-difference interpolation — one of the topics covered in the programme.
A joint programme run with the Mathematical Institute at the University of Oxford, covering mathematical statistics, machine learning, quantitative finance, and frontier results in financial theory.
Taught entirely in English, which was the point as much as the content. It was the first sustained exposure to academic English as a working language, and it changed how I read and write papers.